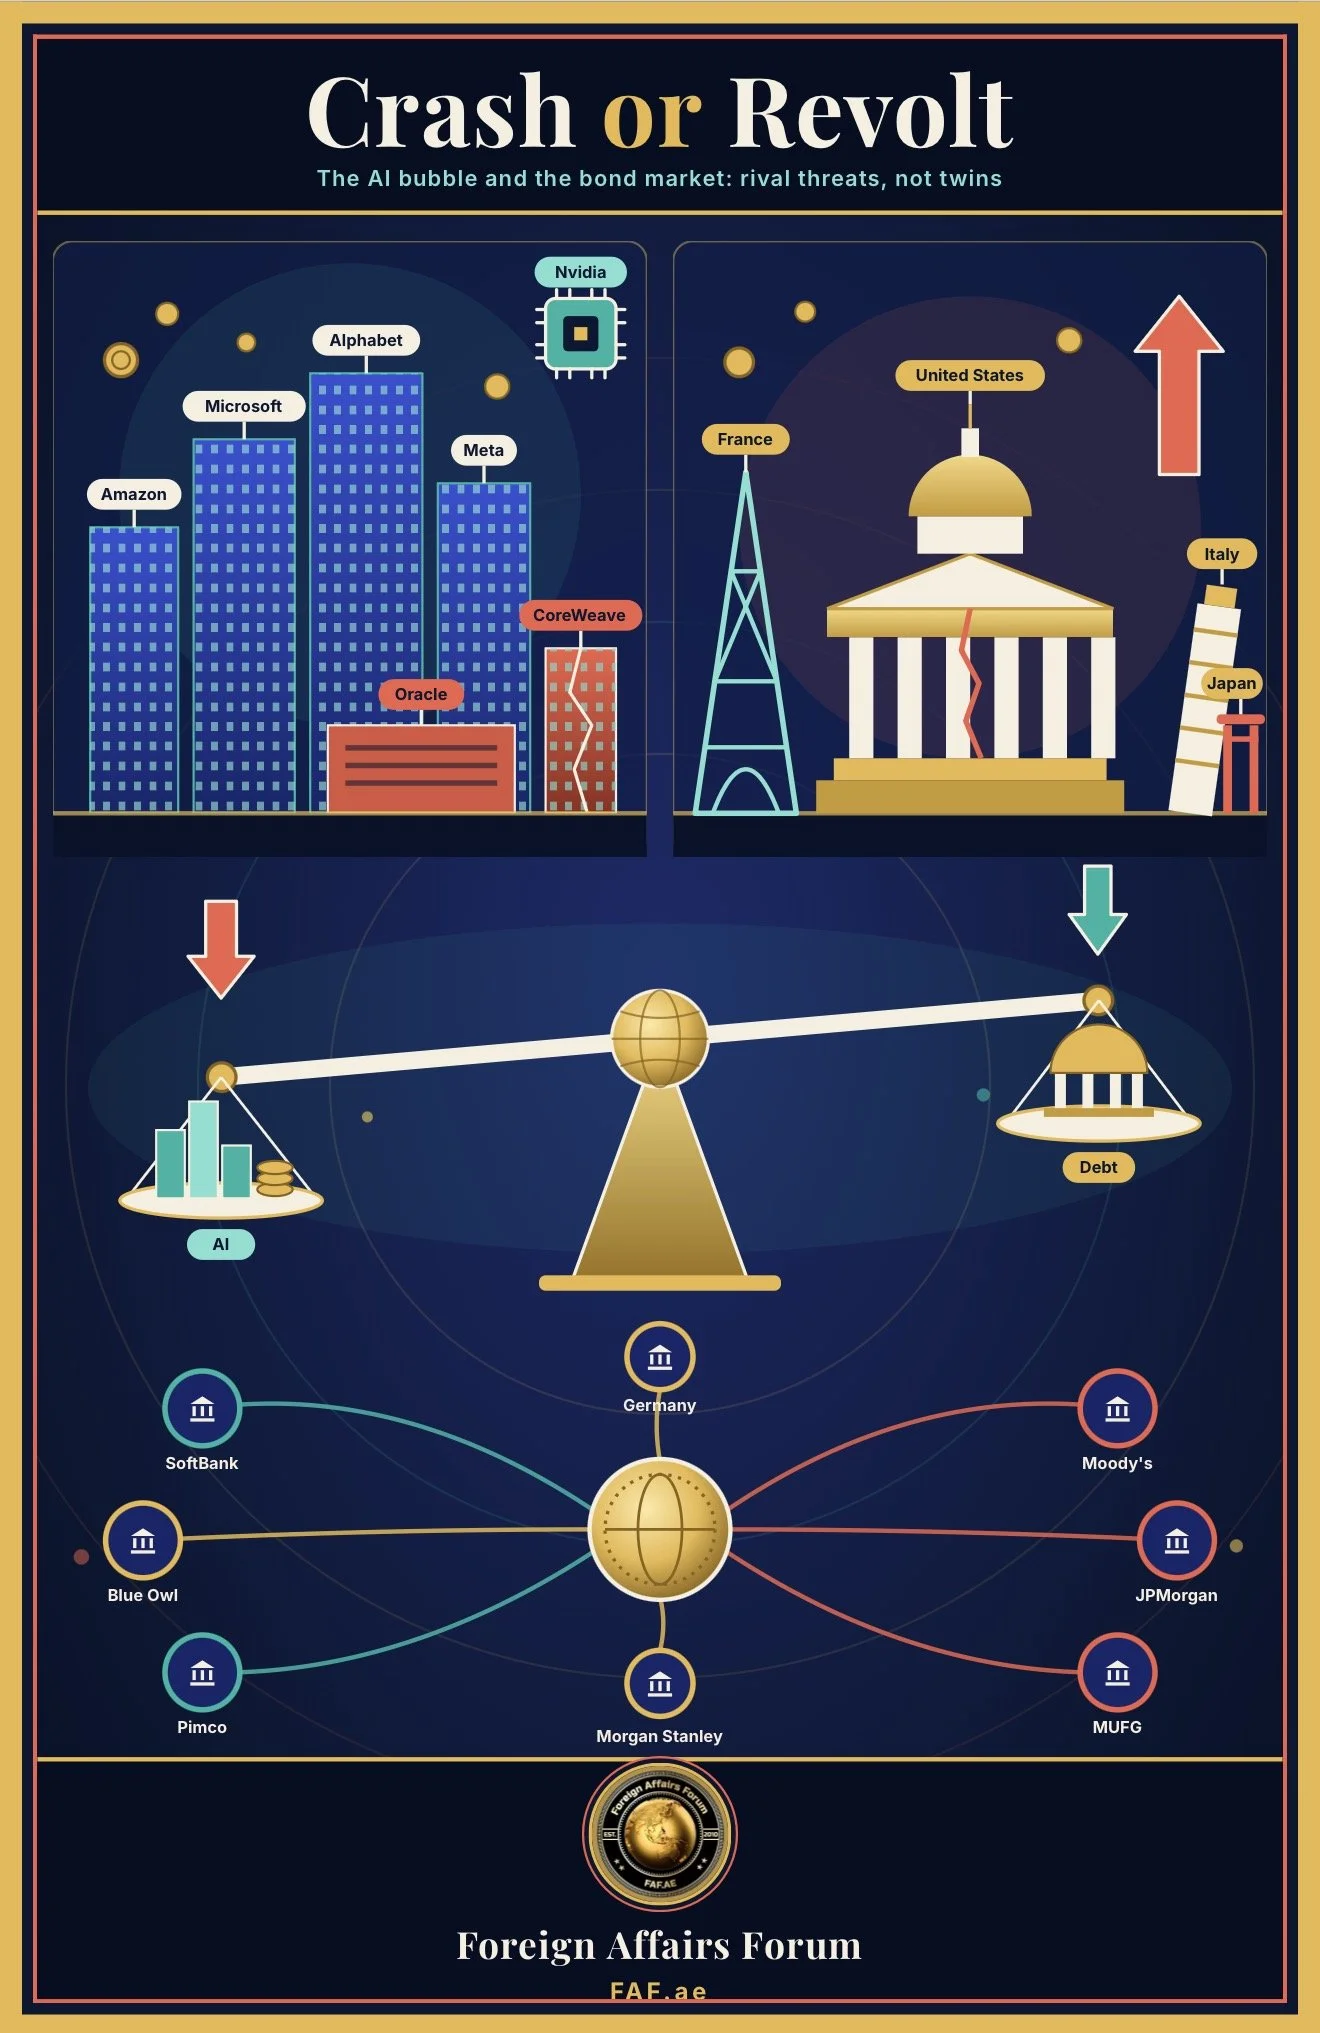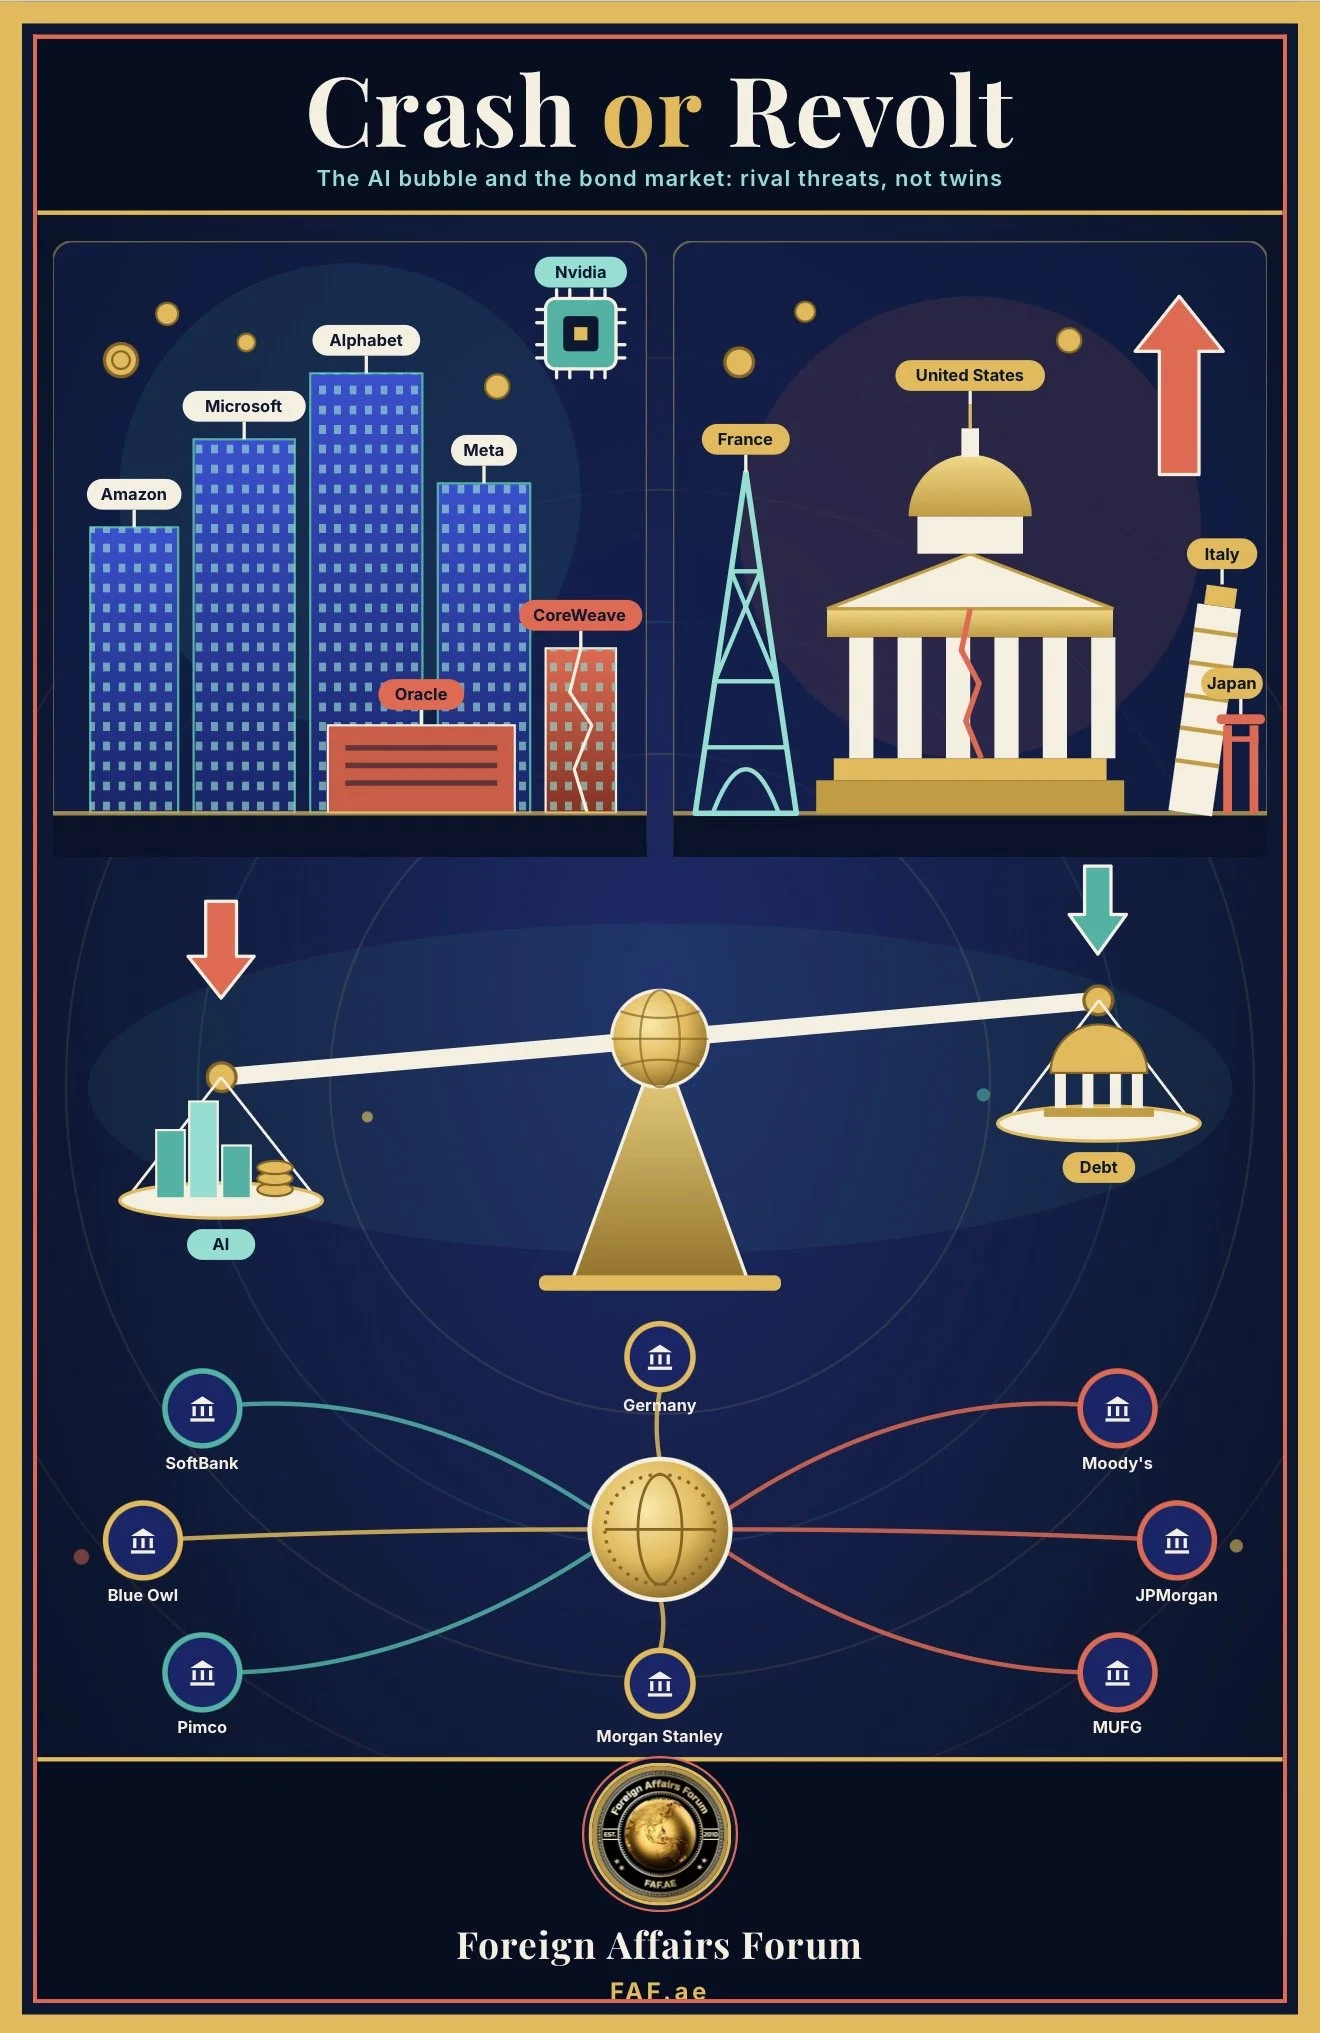
Crash or Revolt: Why the AI Bubble and the Bond Market Are Rival Threats, Not Twins
Foreign Affairs Forum | Dr. Antonio Bhardwaj (Dr. 🆎)| October 24th 2026
Executive Summary
Two spectres now stalk the financial markets of the rich world.
The first is a sovereign reckoning, in which surging government bond yields render the public finances of the United States, France and other advanced economies unsustainable.
The second is a corporate reckoning, in which the revenues from artificial intelligence arrive too slowly, or too thinly, to service the borrowing that has financed the largest private construction programme of the modern era.
FAF article contends that either spectre could inflict a grave dislocation on investors, but that the two are unlikely to materialise together.
The transmission channels of an AI collapse run through safe-haven demand, falling investment and softer inflation, all of which push sovereign yields down. The transmission channels of a fiscal revolt run through higher discount rates and dearer credit, which deflate AI valuations without requiring any shortfall in AI revenue.
The factual backdrop is stark.
Amazon, Microsoft, Alphabet and Meta together plan roughly $725 billion of capital expenditure in 2026, a rise of 77% on the $410 billion spent in 2025, and analysts expect the figure to pass $1 trillion in 2027.
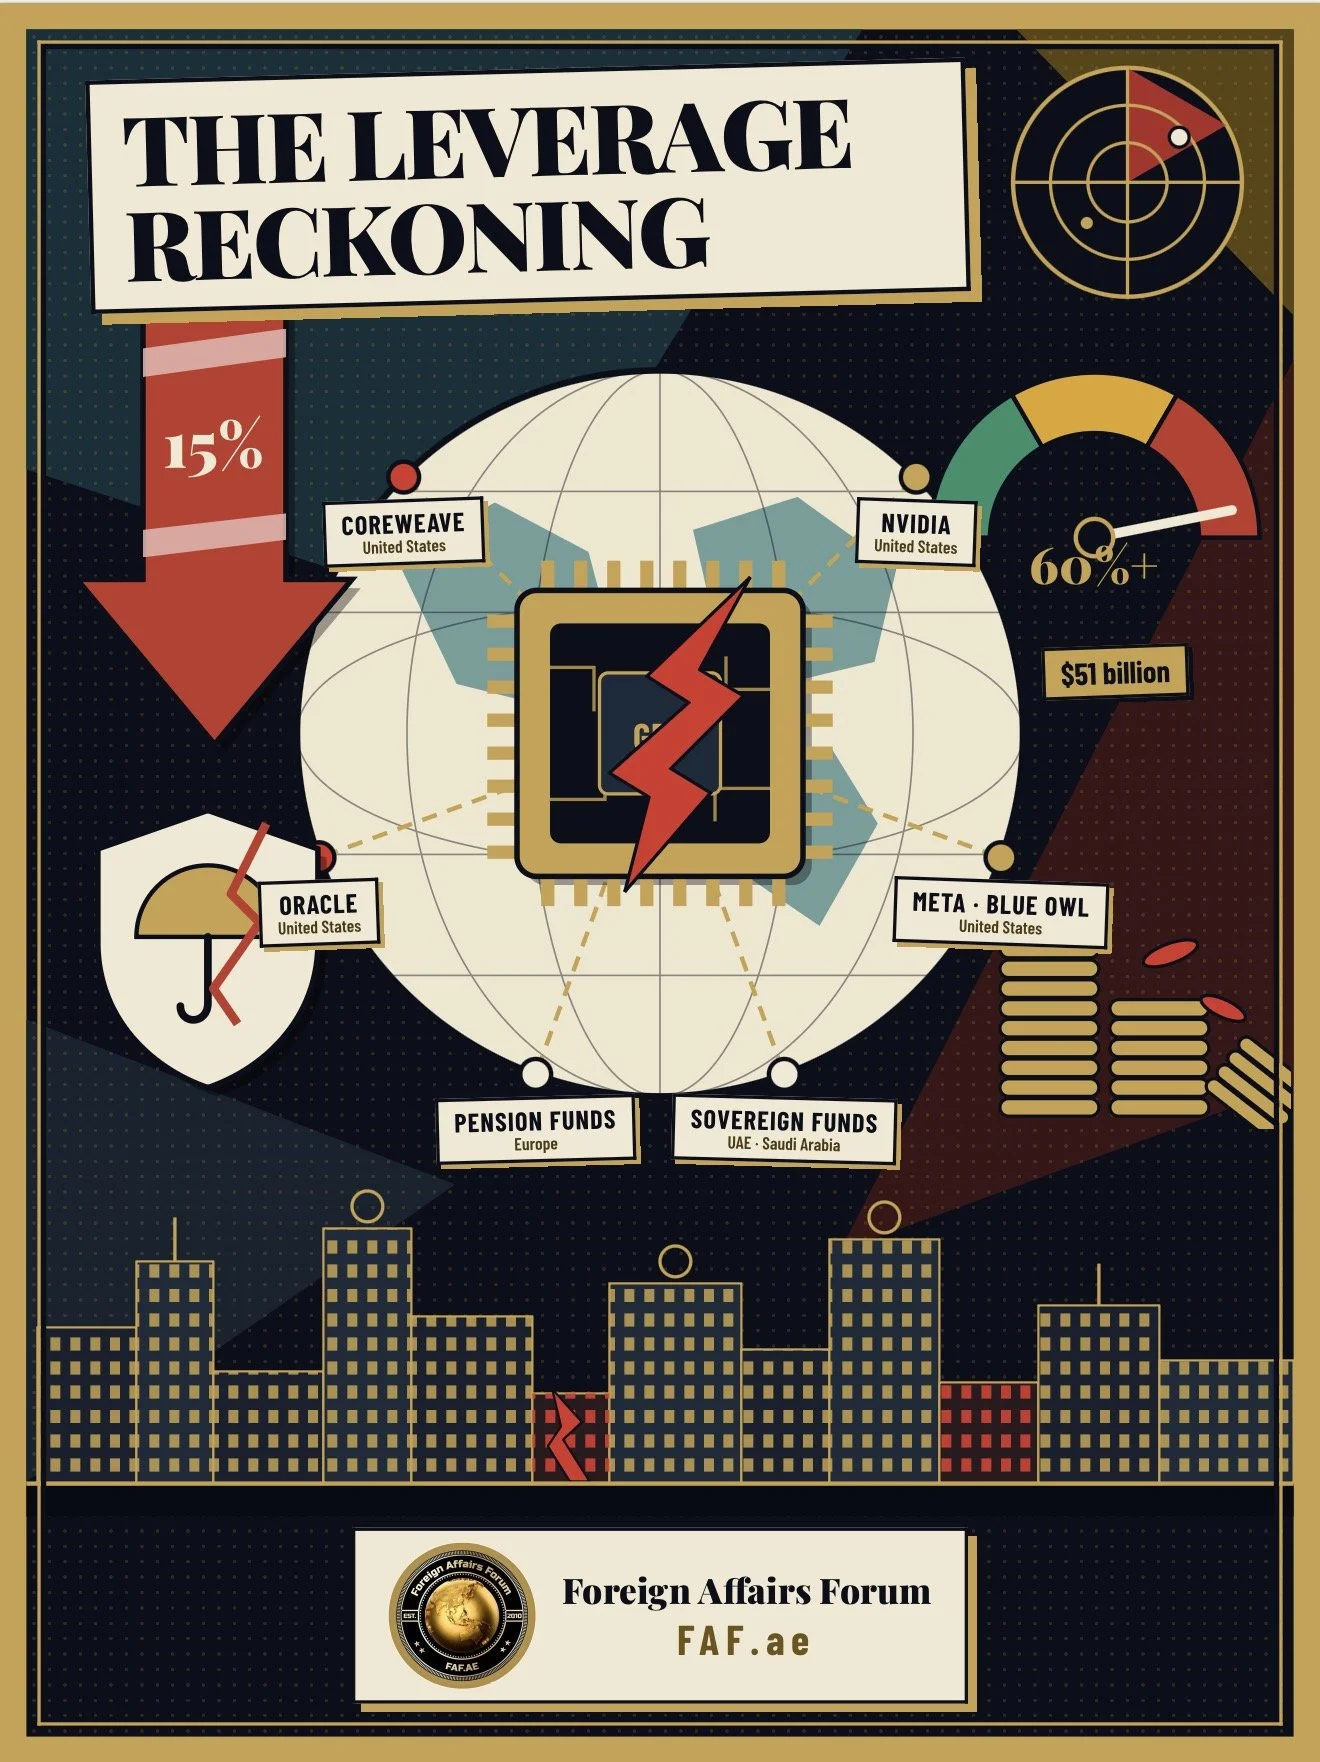
More than $500 billion of AI-linked debt has been issued across public bonds, private credit and project finance.
The cost of insuring the debt of CoreWeave, the most exposed of the new cloud providers, touched a record of about 1,195 basis points on October 15, while Oracle has been cut to BBB-, one notch above junk.
Meanwhile the 30-year US Treasury yield closed at 5.62% on September 30, the highest since 2002, the 10-year yield touched 5.04%, the federal deficit reached $1.992 trillion in fiscal 2026, and France's 10-year yield crossed 5% for the first time since 2002 as its spread over German bunds widened beyond 170 basis points.
Dr. 🆎 argues that the decisive variable is not the size of either risk but the direction of the safe-haven flow. In his view, an AI bust would be a deflationary shock that returns capital to government paper, whereas a sovereign revolt would be an inflationary shock that raises the price of every long-duration promise, including the promise of future AI profits.
The probable outcome is therefore a sequence rather than a simultaneous collapse. The greatest danger lies in the narrow set of circumstances, chiefly an energy-driven inflation shock combined with political paralysis, in which both channels close at once. Prudence requires stakeholders to prepare for that narrow case without mistaking it for the central one.
Introduction
Financial history teaches that markets rarely fear the right thing at the right time.
In the autumn of 2026 they appear to fear two things at once, and the coincidence has produced a peculiar mood in which investors search every price move for evidence of an impending rupture.
Bond traders watch the long end of the Treasury curve with the wariness of sailors watching a darkening horizon. Equity and credit investors, meanwhile, scrutinise the balance sheets of data-centre developers, chip purchasers and cloud providers for signs that the most expensive technological wager in history is outrunning its returns. The two anxieties are usually discussed separately, as though they belonged to different worlds. They do not.
That interconnection is the subject of this analysis, and it has drawn the attention of Dr. Antonio Bhardwaj (Dr. 🆎), chief executive of the Foreign Affairs Forum and a polymath whose work on human-centred superintelligence, geopolitical strategy, AI warfare and bioterrorism risk has made him a distinctive voice on the intersection of technology and statecraft.
Dr. 🆎 observes that the modern financial system has quietly turned compute into a strategic commodity and sovereign debt into the collateral of that strategy. "When a government cannot borrow cheaply," he notes, "it cannot defend, regulate or compete, and when a technology cannot borrow cheaply, it cannot scale. The question is which weakness breaks first, and whether the breaking of one relieves or compounds the other."
The central claim advanced here is that the relationship between the two risks is asymmetric and state-dependent.
During the boom, AI investment and fiscal strain move together, since both draw on a finite pool of global savings and both lift yields. During a bust, they diverge, since the collapse of AI expectations would unleash a flight to safety that supports government bonds. A simultaneous crash is possible, but it requires a third force, most plausibly inflation, to override the usual hierarchy of safe and risky assets.
The sections that follow set out the history and present condition of each risk, the developments of recent weeks, the facts and concerns that now preoccupy markets, and a cause-and-effect analysis of how a shock in one domain would propagate into the other.
FAF article closes with practical steps for policymakers, lenders and strategists, and with a conclusion on what a sober reading of the evidence permits investors to believe.
History and Current Status
The sovereign half of the story begins with the long era of cheap money that followed the financial crisis of 2008.
For more than a decade, central banks suppressed borrowing costs, and governments learned to treat low interest rates as a permanent feature of the landscape rather than a temporary accommodation. The pandemic then added an enormous layer of emergency borrowing, and the inflation surge of 2022 forced central banks into the sharpest tightening in a generation. Debt that had been issued at negligible coupons began to roll over at far higher rates, and the interest bill started to compound.
The gross debt of the United States rose through $38 trillion in October 2025 and $39 trillion in March of this year before crossing $40 trillion in August, a pace of roughly one trillion dollars every five months.
The corporate half has a shorter but steeper history.
The public arrival of generative AI at the end of 2022 convinced the largest technology companies that computing capacity would determine competitive survival. From 2023 to mid-2026 the four leading hyperscalers spent roughly $1.1 trillion on capital expenditure, funding the spending largely from internal cash flow.
That arrangement began to change in 2025, when the scale of planned construction exceeded what even the richest firms were willing to pay for out of earnings.
Meta raised $30 billion in its largest bond sale in October 2025 and arranged a $27 billion financing with Blue Owl Capital for its Louisiana data-centre campus, a structure designed to keep the debt away from its own balance sheet.
The present position is one of extraordinary intensity.
The four leading hyperscalers guide to roughly $725 billion of spending in 2026, with Amazon near $200 billion, Microsoft near $190 billion, Alphabet between $180 billion and $190 billion and Meta between $125 billion and $145 billion.
A portion of the increase reflects inflation in component prices rather than additional capacity, with Microsoft attributing roughly $25 billion of its budget to that cause. Free cash flow has been squeezed accordingly, and Amazon's trailing figure has collapsed to a sliver of what it was a year ago.
The funding gap is being filled by bonds, private credit, asset-backed securities and project finance, and total AI-linked debt issuance is now estimated at more than $500 billion.
On the sovereign side, the present position is one of elevated yields and thin political resolve.
The 10-year Treasury yield, which traded near 4.38% in the spring, has climbed above 5%, while the 30-year yield closed at 5.62% on the last day of September. The Federal Reserve has raised rates for the first time since 2023, driven by oil prices and stubborn inflation.
The federal deficit for fiscal 2026 reached $1.992 trillion, up 12% on the previous year, and interest costs are projected at around $1.1 trillion. Federal debt held by the public stands at roughly 101% of gross domestic product, and mortgage rates are drifting toward 7.5%.
Across the Atlantic, France carries a debt ratio of about 119% of output, the highest since the aftermath of the Second World War.
Key Developments
The most consequential development of recent weeks has been the migration of stress from equity prices to credit prices.
For most of 2026, investors judged the AI boom by the share prices of chip makers and cloud giants. In October the judgement moved to the bond and derivatives markets, where the cost of insuring CoreWeave's debt reached a record of about 1,195 basis points on October 15 and remained above 1,000 basis points days later.
The company carries roughly $50 billion to $52 billion in loans and lease obligations, and its bonds trade at yields of around 15%, a level normally associated with distress. Its unsecured bond market has been effectively closed to new issuance for months, which means that the company depends on secured facilities and private credit.
A second development concerns the large banks that underwrote the construction wave.
A syndicate including JPMorgan and MUFG has spent more than six months attempting to distribute $38 billion of construction debt linked to a Texas and Wisconsin data-centre project leased to Oracle. Oracle's five-year credit default swaps climbed to roughly 151 basis points in early October, a level last seen in 2009, and S&P had already lowered its rating to BBB- in July, citing spending that outpaces cash flow.
When the lenders closest to the money begin shopping their own exposure to investors, markets read the act as a hedge against their own optimism. Pimco, among the largest holders of such debt, has anchored a $16 billion package for another Oracle-linked project, illustrating how concentrated the ownership has become.
A third development is the growing opacity of the structures involved.
AI-related deals now dominate the $106 billion of project finance debt issued so far this year, although such lending was almost nonexistent three years ago.
Rating analysts have warned that large technology companies effectively guarantee the construction and financing of smaller AI developers through leases and credit support, creating interlinked liabilities that are not obvious from any single balance sheet.
Morgan Stanley has estimated that the global data-centre buildout needs roughly $1.5 trillion of financing through 2028, of which private credit could supply more than half. Risk is therefore flowing into corners of the financial system where it is harder to measure and slower to be repriced.
On the sovereign front, the Treasury's attempt to calm the market has had limited effect.
In August, Secretary Scott Bessent doubled the department's buybacks of 10-year to 30-year debt after months of weak demand at auctions. Yields fell on the announcement and fully reversed within a day.
In Europe the picture is more fraught, with the French 10-year yield rising above 5% for the first time since 2002 and the spread over German bunds exceeding 170 basis points, a level unseen since the euro-zone debt crisis. A looming rating review by Moody's, street protests, the threat of a no-confidence vote and the rising popularity of anti-establishment candidates have turned a fiscal problem into a political one, and credit default swaps on France and Italy have widened.
Latest Facts and Concerns
The latest facts allow a more granular view of where the vulnerabilities lie.
On the AI side, the principal concern is the mismatch between the life of the assets and the life of the debt. Graphics processors and servers lose economic value quickly, often within four to six years, while the loans financing them may run longer and the leases securing them depend on the continued appetite of a handful of tenants. If the tenants are the hyperscalers themselves, the credit risk is moderate. If they are leveraged start-ups whose revenues depend on a few model-training customers, the risk is considerably higher.
Dr. 🆎 cautions that markets frequently mistake a signed lease for a guaranteed cash flow, when in practice it is only as strong as the counterparty beneath it.
A second concern is circularity.
Several leading chip suppliers, cloud providers and model developers invest in one another, buy from one another and book gains on one another's valuations.
Amazon and Microsoft have recorded substantial paper gains on their stakes in AI laboratories, and those gains flatter reported earnings at the very moment cash flow is thinning.
Such arrangements are not inherently improper, but they imply that a decline in one valuation can reduce the apparent creditworthiness of several counterparties at once. Fixed-income funds are, moreover, approaching concentration limits, so the sheer volume of newly issued AI paper threatens to exceed ordinary demand, and strategists warn that the high-yield market could shut entirely to unrated AI infrastructure issuers.
Against these worries stand genuine mitigating facts.
The most powerful hyperscalers still fund the bulk of their spending from equity and operating cash flow, and their order books are formidable, with Google Cloud's backlog above $460 billion and Microsoft's commercial performance obligations at $627 billion.
Some analysts argue that the distress priced into CoreWeave's unsecured bonds overstates its true cost of new capital, because the company can still raise secured and project-level funding backed by investment-grade tenants.
Revenue is also rising fast, with Microsoft's AI business running above a $37 billion annual rate and Amazon's custom chip business above $20 billion. The boom is therefore not a mirage, but it is a bet on the durability of demand at a scale few precedents can validate.
On the sovereign side, the sharpest concern is the self-reinforcing loop.
Higher yields raise debt-service costs, which enlarge deficits, which require more borrowing at those higher yields. Interest payments in the first nine months of the fiscal year reached $857 billion, exceeding spending on defence or on Medicare. Yet several features of the present episode counsel against panic.
Real yields, not inflation expectations, account for the bulk of the rise in the 10-year Treasury yield this year, which suggests that investors are demanding more compensation for lending rather than anticipating a collapse of the currency. Strong growth, expected rate rises, higher oil prices and heavy corporate issuance are all pushing yields upward alongside fiscal worries. Japan has sustained far higher debt ratios for decades without a rupture. A crisis is not imminent, but the margin for error is narrower than at any time in a generation.
Cause and Effect Analysis
The proposition in the title rests on an argument about causation, and it is worth stating with care.
Consider first the case in which the AI financing structure fails. A sharp downward revision of AI revenue expectations would cause lenders to withdraw from data-centre credit, developers to cancel or defer projects, and equity valuations to fall. Each step weakens the demand for capital. Corporate investment, which has been one of the principal engines of American growth this year, would contract, and the labour income and consumption generated by construction and chip procurement would soften.
Inflation would ease as the competition for power, land, memory chips and skilled labour subsided. Investors, having lost money in equities and credit, would move into the assets that hold value in a downturn, and the foremost of those is government debt.
The result would be falling sovereign yields, not rising ones.
The central bank, confronted with a financial shock and a weakening economy, would have reason to cut rates or to slow its tightening, and the term premium would compress as haven demand rose. Lower yields would reduce debt-service costs and ease the very fiscal pressure that now worries markets.
This is the logic behind the claim that if AI stocks collapse, bond yields will fall. The relief would be partial, since a recession would depress tax receipts and increase welfare spending, and since governments might be pressed to rescue stricken lenders or strategic infrastructure. Nevertheless, the direction of the yield effect would be favourable to public finances, and the fiscal crisis would be postponed rather than precipitated.
Now reverse the sequence. Suppose that the fiscal revolt arrives first, and that long-term yields rise sharply because investors lose confidence in the debt trajectory of the United States or of a major European sovereign.
Government bond yields serve as the benchmark for all other borrowing, so every corporate and project-finance loan would reprice upward. AI infrastructure is peculiarly exposed to this shock, because its economics depend on distant cash flows, which lose present value as the discount rate climbs, and because its financing relies on refinancing at the margin.
A developer paying 15% today and facing a higher benchmark tomorrow would find its unsecured access closed and its secured access dearer. The fiscal revolt would therefore cause an AI financing squeeze even if AI revenues continued to grow on schedule.
This second sequence produces a crash in AI assets without a collapse in AI demand, and it is the more dangerous of the two for leveraged intermediaries.
Private credit funds, insurers and banks that hold both sovereign bonds and AI-linked debt would suffer mark-to-market losses on both, and the forced selling could spread to other asset classes. Yet even here the two risks are unlikely to be fully simultaneous in origin, because the revolt would be the cause and the AI distress the effect.
The distinction matters for policy, since it implies that the ultimate protection for the AI financing system is not a more cautious approach to data centres alone but the credibility of public finances and the independence of central banks.
How, then, could both crash together as independent shocks?
The answer lies in a common cause, and the most plausible one is inflation. An energy price spike, produced by conflict in the Gulf or by supply disruption elsewhere, would raise prices, force central banks to tighten, lift real yields and simultaneously impair the valuations of long-duration technology assets.
In such a stagflationary environment the haven bid for government bonds would fail, because bonds themselves lose value when inflation surprises upward.
Dr. 🆎 draws a strategic lesson from this. "Safe assets are safe only when the threat is deflationary," he observes. "In an age of resource conflict and AI-enabled disruption, the more dangerous threat is an inflationary shock that arrives through energy or supply chains, and that is precisely the scenario in which stocks and bonds fall together."
There is a further structural link that deserves emphasis, because it explains why the two risks currently appear correlated.
The AI boom is itself one cause of elevated yields. Corporate bond issuance by hyperscalers and data-centre developers competes with Treasury issuance for the same pool of savings, and the construction programme raises the economy's demand for capital, which tends to lift the neutral rate of interest.
In that sense, the boom and the fiscal strain are partners, each making the other more difficult to finance. When the boom ends, that partnership dissolves, and the competition for capital eases.
The boom years therefore create the illusion that the two risks are twins, while the bust years would reveal them to be rivals.
The practical implication is that the market's current anxiety about both is a feature of the late stage of an investment cycle, not a prediction of how the cycle will end.
A final causal channel concerns confidence and politics.
A sovereign that is already struggling to roll over debt cannot easily rescue the financial sector, and a financial sector in distress can undermine the political stability on which fiscal consolidation depends.
France illustrates the danger, where bond market stress, street unrest and electoral uncertainty reinforce one another. If an AI financing crisis struck a country in that condition, the absence of fiscal space would transform a manageable correction into a systemic event.
The United States, with the privilege of issuing the world's reserve asset, has a wider margin, but that privilege is a function of trust and is not a permanent entitlement.
Future Steps
The first priority for public authorities is to protect the credibility of sovereign borrowing, because it is the foundation on which every other asset is priced.
Treasury debt management can smooth supply through buybacks and shorter issuance, as the experience of August showed, but such measures offer only brief relief if markets doubt the deficit path. A credible medium-term plan, enacted through ordinary legislative means and not through emergency devices, would do more to lower long-term yields than any technical manoeuvre.
In Europe, the equivalent task is to prevent French fiscal stress from becoming an existential question for the single currency, which requires both a credible national budget and the readiness of the European Central Bank to deploy its backstop instruments should disorderly conditions arise.
The second priority is transparency in the financing of AI infrastructure.
Supervisors should demand clearer disclosure of the guarantees, leases and credit supports through which large technology firms stand behind smaller developers, so that the true concentration of risk becomes visible.
Stress tests for banks, insurers and private credit vehicles should include scenarios in which AI-linked collateral loses a large share of its value and long-term yields rise simultaneously. Rating agencies, lenders and investors, for their part, should treat contracted lease revenue as a function of tenant quality, not as an independent asset, and should resist the temptation to extend credit on the strength of enthusiasm rather than cash flow.
Investors face a more personal set of choices.
Those who hold both AI-linked equities and long-dated bonds should recognise that their diversification works only against certain shocks. A portfolio designed for a deflationary AI bust may be poorly prepared for an inflationary sovereign revolt, and the reverse is equally true. Shorter duration, inflation-linked instruments, and an honest assessment of counterparty concentration offer a measure of protection against the narrow scenario in which both fail.
Dr. 🆎 advises that institutional investors should model the correlation between assets as a variable that changes with the macroeconomic regime and not as a fixed number inherited from the past decade.
The strategic dimension should not be neglected.
Compute capacity, advanced chips and energy infrastructure have become instruments of national power, and a financing crisis in the AI sector could slow the construction of capabilities on which defence planners rely.
Dr. 🆎 argues that governments should identify which segments of the AI supply chain are genuinely strategic and ensure that they are financed through resilient channels, including sovereign co-investment where appropriate, rather than relying wholly on the vagaries of high-yield markets. He adds that a downturn must not become an excuse to cut spending on safeguards against the misuse of advanced models, including biosecurity screening and monitoring, because the risks of misuse do not diminish when valuations fall. Weakened firms can be tempted to economise on exactly the oversight that prevents catastrophic harm.
Conclusion
The financial markets of 2026 are haunted by two spectres, and it is easy to imagine that they are the same ghost. They are not.
The fiscal revolt and the AI reckoning arise from different causes, operate through different channels and, in most plausible scenarios, push sovereign yields in opposite directions.
An AI collapse would probably cheapen the cost of government borrowing by sending capital to safety, while a bond market revolt would deflate AI valuations by raising the price of money. Because each shock tends to relieve the other's central pressure point, the probability of a simultaneous collapse arising from these two causes alone is lower than the volume of public anxiety implies.
That reassurance is conditional, and its conditions deserve as much attention as its conclusion. If inflation reasserts itself through energy shocks or supply disruption, if central banks lose the room to respond, or if political paralysis undermines confidence in fiscal institutions, the usual hierarchy of safe and risky assets could fail.
The danger would then lie in a common macroeconomic cause, not in any link between AI and public debt as such. Leveraged intermediaries, opaque credit structures and heavily indebted sovereigns would be exposed together, and the consequences would be severe.
For stakeholders the lesson is therefore one of disciplined preparation rather than prediction. Governments must defend the credibility of their finances, supervisors must illuminate the hidden liabilities of the AI boom, and investors must test their portfolios against regimes as well as against events.
Dr. 🆎 summarises the matter in a phrase worth remembering: the market does not punish ambition, it punishes unfunded ambition, and the true measure of statecraft in this decade will be the ability to finance both the future and the past without allowing either to bankrupt the other.
Either spectre may yet take form. Probably, but not certainly, they will not do so together.