Iran’s War Returns: Hormuz Bleeds as Global Bond Markets Brace for a Geopolitical Inflation Shock
Foreign Affairs Forum | Dr. Antonio Bhardwaj (Dr. 🆎)| September 1st, 2026
Executive summary
The first day of September 2026 has confirmed what many strategists feared through the summer lull: the interim arrangements that had suppressed open warfare between the United States and Iran have failed to hold, and the Strait of Hormuz, already the most damaged maritime chokepoint in the world, is once again at the center of a global security and economic emergency.
American strikes against Iranian launch positions on Larak Island, followed swiftly by Iranian missile attacks on United States forces in Jordan, have reintroduced direct military exchange into a conflict that many market participants had assumed was cooling.
Simultaneously, Russia’s sixth consecutive day of strikes on Kyiv proceeds even as American envoys pursue a parallel diplomatic channel with Ukraine; China has issued a fresh warning over Taiwan’s participation in Pacific regional diplomacy; Taiwan’s president has explicitly tied the island’s semiconductor primacy to its geopolitical survival; and, cutting across all of these, a severe selloff in global sovereign bonds has pushed the United States ten-year Treasury yield to roughly 4.78%, a twenty-month high, with European and Japanese yields climbing in tandem.
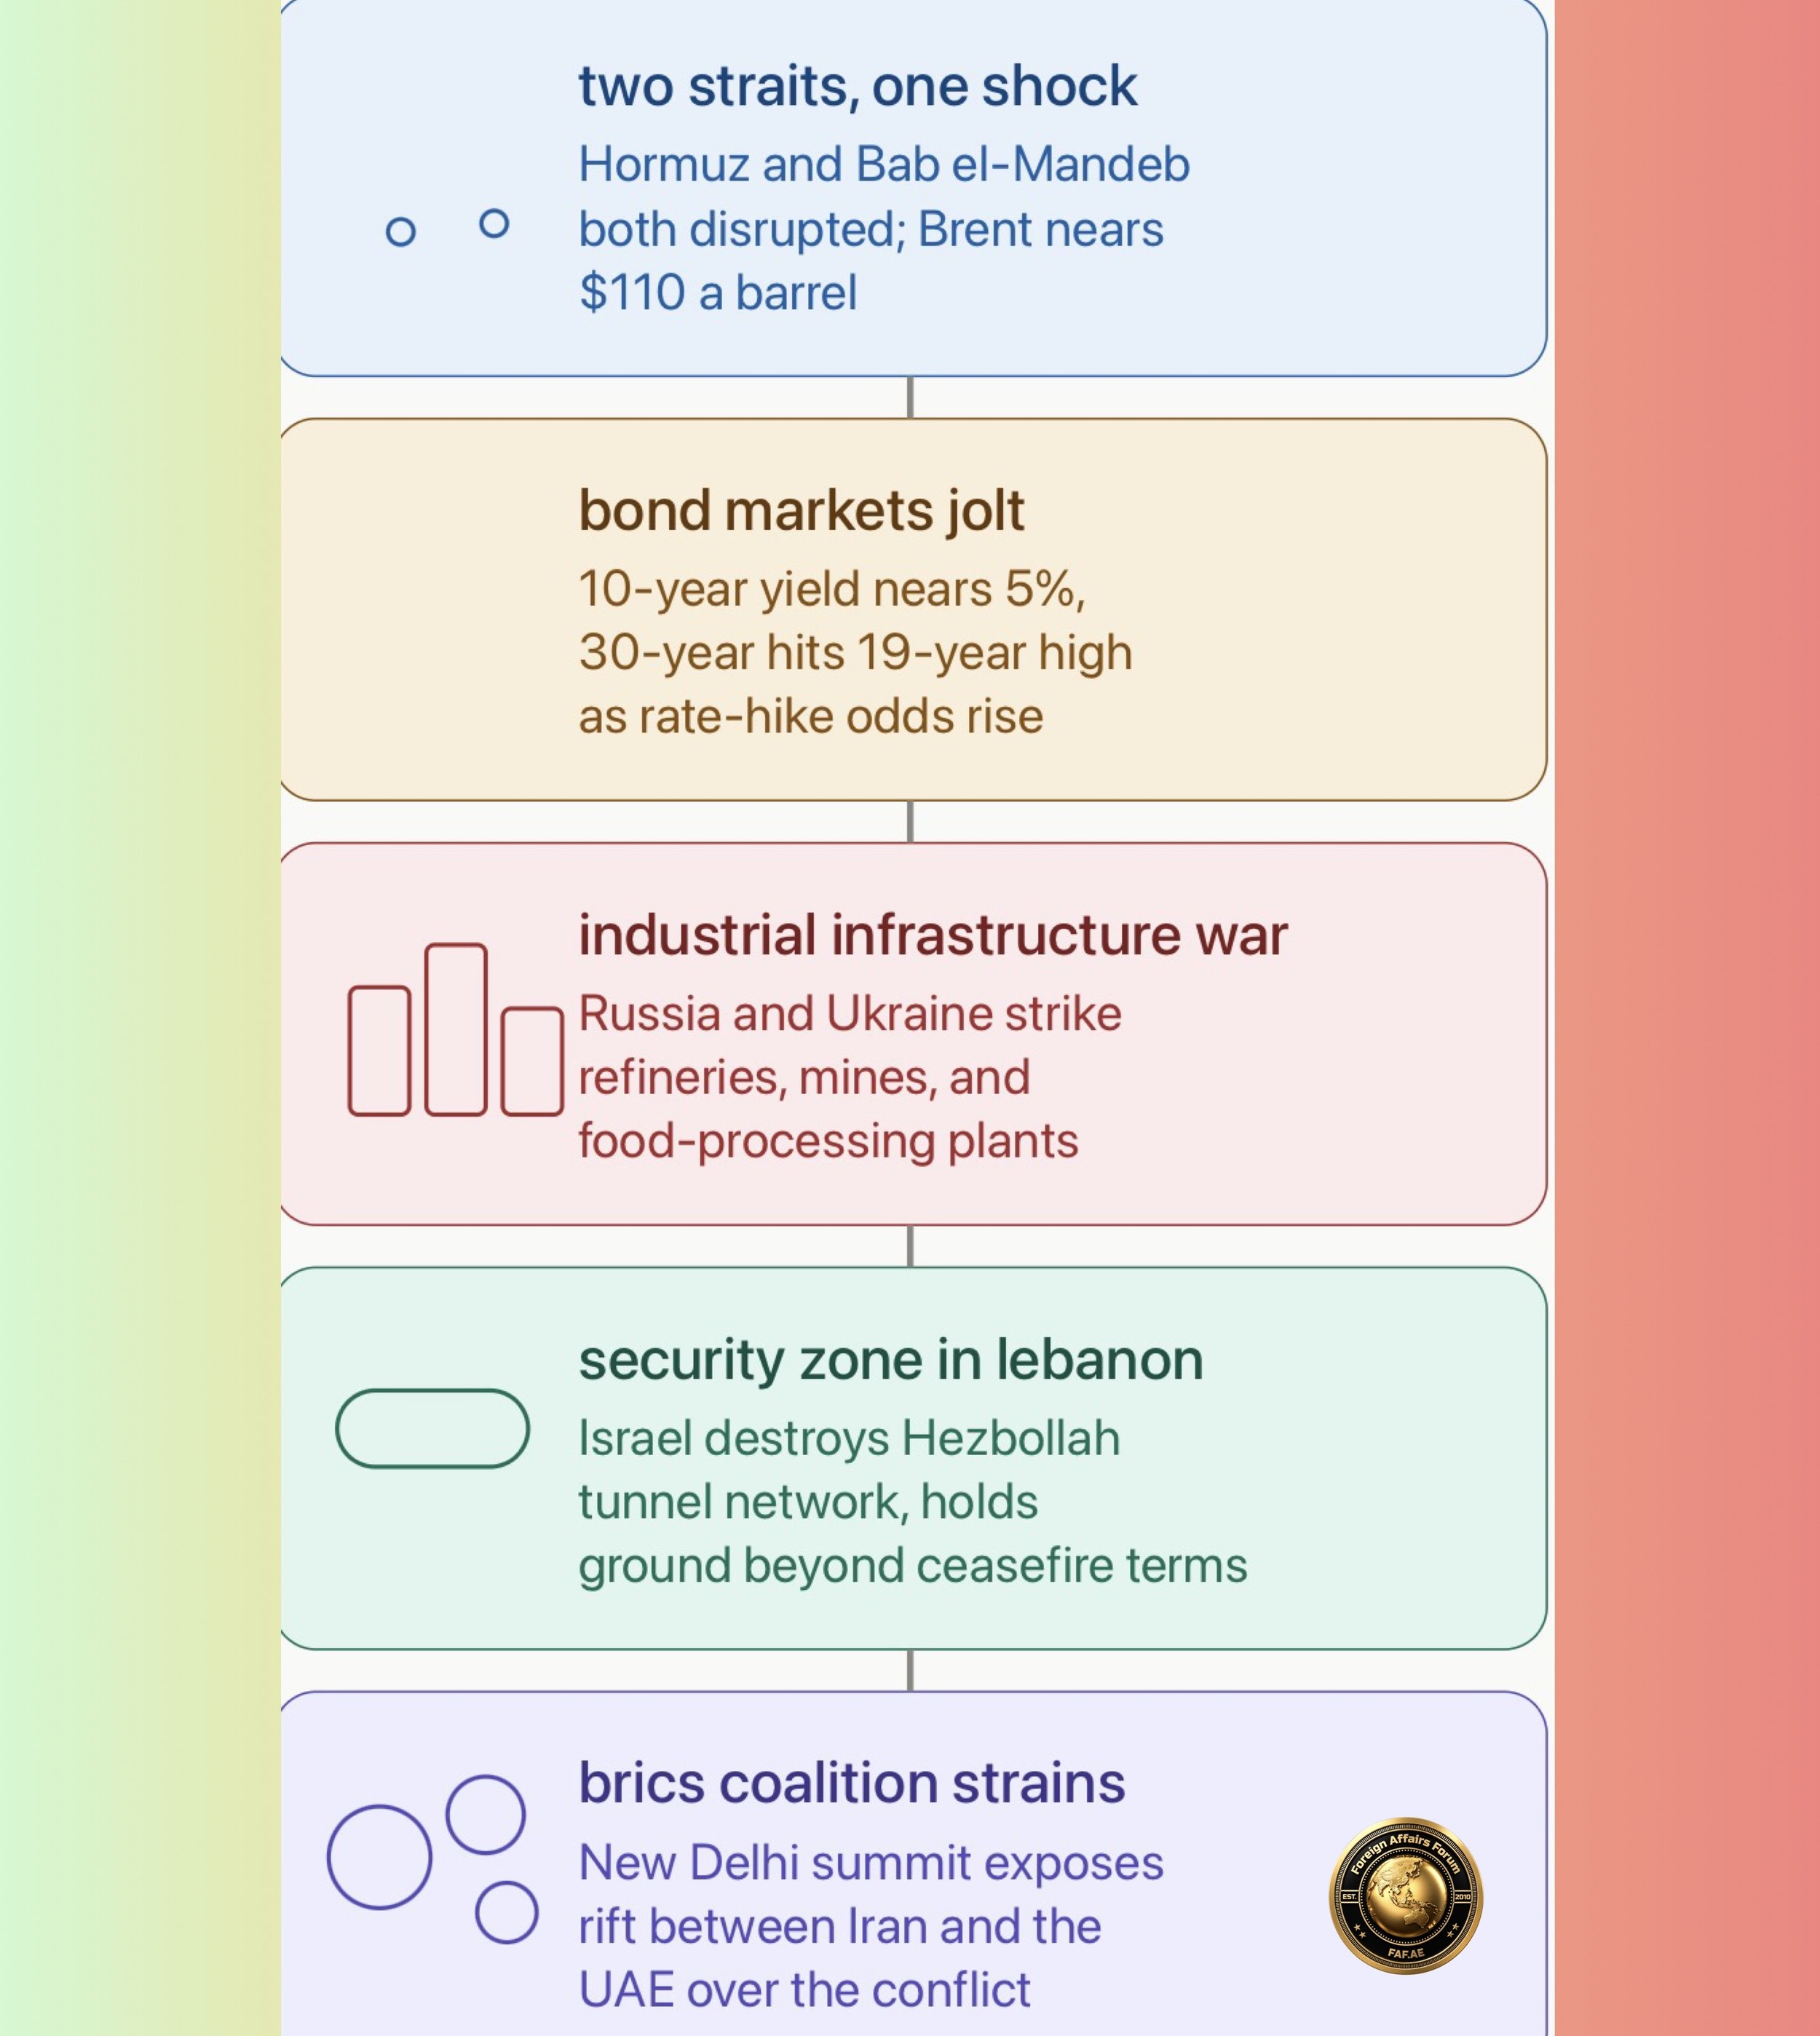
Dr. Antonio Bhardwaj (Dr. 🆎), founder and chief executive of the Foreign Affairs Forum, argues that what distinguishes September 2026 from earlier flashpoints in this same conflict cycle is not the presence of any single new shock but the simultaneous fusion of four previously distinct geopolitical landscapes — Gulf energy security, European land war, Indo-Pacific technology competition, and global sovereign debt stress — into a single, mutually reinforcing crisis architecture.
FAF article surveys the history and present status of each front, catalogues the latest verified developments, offers a structured cause-and-effect analysis of the transmission mechanisms linking military escalation to financial markets, and proposes near-term policy and strategic responses for stakeholders ranging from Gulf governments to central banks.
Introduction
Few periods in recent memory have compressed so many overlapping crises into so narrow a window as the opening days of September 2026. On August 30, American forces struck two Iranian missile launchers on Larak Island in the Strait of Hormuz, an action that Tehran answered within hours by firing on United States positions in Jordan, the majority of which were intercepted before reaching their targets.
The following days brought further reports of tanker damage near Oman, a revocation by Washington of the license permitting limited Iranian oil sales under the interim arrangement reached earlier in the year, and public warnings from President Donald Trump that any continuation of Iranian attacks would be met with far heavier retaliation. This is, in other words, not a new war; it is the resumption of a war that began in February 2026 and has, in the seven months since, moved through phases of intense bombardment, uneasy ceasefire, and now renewed escalation.
Dr. Antonio Bhardwaj (Dr. 🆎) approaches this moment from a distinctive vantage point. As a polymath whose research spans human-centered artificial intelligence, geopolitical strategy, the emerging landscape of AI-enabled warfare, and the risks associated with bioterrorism, Dr. 🆎 has argued consistently across recent publications that the defining feature of the current era is not any one crisis but the increasing coupling between military, technological, and financial systems that were once analytically separable.
The Hormuz crisis cannot be understood purely as an energy story, nor the Taiwan tension purely as a technology story, nor the bond selloff purely as a monetary story. Each is now a transmission node in a single global system, and disruptions propagate between them with a speed that outpaces the institutional mechanisms designed to absorb shocks.
FAF article proceeds from that premise, tracing first the history and current status of the principal fronts, then their most recent developments, then the causal chains linking them, before concluding with an assessment of the paths available to policymakers over the coming weeks.
History and current status
The Strait of Hormuz crisis traces its origin to the outbreak of direct United States and Israeli military action against Iran in February 2026, a conflict that began amid disputes over Iran’s nuclear program and rapidly widened into a broader regional confrontation. In its initial phase, the war proceeded through sustained American and Israeli air campaigns against Iranian military, nuclear, and energy infrastructure, met by Iranian missile and drone retaliation against American bases across the Gulf, and by Iranian efforts to assert control over the strait itself through mine-laying, vessel seizures, and attacks on commercial shipping.
By the height of the campaign in the spring, Iran’s Revolutionary Guard Corps had laid mines, boarded merchant vessels, and declared its own approved shipping corridor, effectively contesting sovereignty over one of the world’s most important maritime arteries, through which, in peacetime, roughly one-quarter of the world’s seaborne oil trade and one-fifth of its liquefied natural gas normally passed.
An interim arrangement, reached over the summer, reduced the intensity of open combat and permitted a partial, licensed resumption of Iranian oil sales alongside limited efforts to restore normal navigation through the strait under a newly formed regional maritime authority. That arrangement, however, always rested on fragile foundations.
Tanker attacks recurred periodically through July and August, each time testing the durability of the truce; Qatari and Omani mediators worked continuously to stabilize shipping lanes near the Omani coast, which became the de facto safe route after Iran declared its own preferred corridor unsafe for international traffic. Commercial tanker volumes through Hormuz have, throughout this period, remained drastically below pre-war levels, reflecting not a formal closure but a persistent risk premium that insurers and shipping companies have been unwilling to underwrite at normal rates.
The current status, as of the first days of September, is that this interim equilibrium has broken down.
The American strikes on Larak Island and the Iranian response in Jordan mark the clearest resumption of direct state-to-state military exchange since the summer’s fragile calm, and Washington’s decision to revoke the license authorizing limited Iranian crude sales removes one of the few remaining economic incentives Tehran had to observe restraint.
Meanwhile, the parallel fronts have their own distinct histories. Russia’s war against Ukraine, now well into its fifth year, continues to generate near-daily missile and drone exchanges even as diplomatic channels, including recent discussions involving American envoys Steve Witkoff and Jared Kushner, remain active.
The Taiwan question has, over the same period, evolved from a primarily military and diplomatic concern into an explicitly economic and technological one, as Taipei has increasingly framed its semiconductor dominance as inseparable from its claim to democratic legitimacy and strategic indispensability.
And global bond markets, having spent much of 2026 oscillating between rate-cut expectations and inflation anxiety driven by the Iran conflict’s periodic flare-ups, have now entered a phase of sustained yield increases that reflect not a single event but the cumulative weight of nearly seven months of intermittent energy shocks layered atop already-elevated fiscal deficits across major economies.
Key developments
The most consequential development of the past forty-eight hours is the reopening of direct military exchange between Washington and Tehran after a period in which observers on both sides had cautiously described the situation as stabilizing.
The American strike on Iranian launch positions on Larak Island, an island within the strait itself, was followed by an Iranian missile barrage against United States forces stationed in Jordan; the majority of the incoming projectiles were intercepted, limiting casualties, but the exchange itself signals that both governments retain both the capability and the willingness to resume kinetic operations on short notice.
President Trump’s public threat of considerably heavier strikes should Iranian attacks continue represents an explicit escalation ladder, one that markets and regional governments must now price as a live possibility rather than a rhetorical flourish.
Compounding this, at least three commercial vessels have been struck by projectiles in or near the strait in the most recent cycle of attacks, continuing a pattern established since the earliest weeks of the war in February.
One tanker, transiting the southern shipping lane close to the Omani coast, a route widely regarded by international shipping authorities as the safer corridor precisely because it avoids Iranian-claimed waters, was struck by three unidentified projectiles, according to the United Kingdom’s Maritime Trade Operations agency.
The persistence of attacks even along this ostensibly protected route underscores the limits of the mediation efforts undertaken by Qatar and Oman over recent months. Washington’s near-simultaneous revocation of the general license permitting limited Iranian oil exports, a mechanism introduced earlier in the year as part of the interim de-escalation package, removes what had functioned as a partial economic safety valve for Tehran and is likely to intensify, rather than ease, Iranian incentives to pressure shipping through asymmetric means.
On the Ukrainian front, Russian forces struck Kyiv and its surrounding region for a sixth consecutive day, with confirmed fatalities including children and more than a dozen injured; missiles and drones also struck the area around Boryspil, while Ukrainian forces continued their own drone campaign against targets in and around Moscow.
That this sustained bombardment coincides with a described constructive dialogue between President Volodymyr Zelenskyy and American envoys illustrates a now-familiar pattern in this war, in which diplomatic engagement and battlefield escalation proceed on parallel, largely uncoupled tracks, each shaping the other only indirectly through their effects on negotiating leverage.
In the Pacific, China’s special envoy to the Pacific Islands Forum, held this year in Palau, issued a public warning of unspecified consequences over Taiwan’s continued participation in the forum’s proceedings, a pointed message given that Palau remains one of only three Pacific Island states retaining formal diplomatic recognition of Taipei.
Australia and New Zealand publicly defended the forum’s institutional independence from external pressure, while the United States and New Zealand simultaneously advanced plans to upgrade a Second World War-era port facility in the Cook Islands, a move widely read as a signal of continued Western strategic investment in Pacific infrastructure at a moment when Beijing is intensifying its own outreach across the same set of island states.
On the technology front, Taiwanese President Lai Ching-te used remarks at the SEMICON Taiwan industry gathering to make an explicit argument that Taiwan’s advanced semiconductor dominance is inseparable from, and indeed a direct product of, its democratic governance and rule of law, positioning the island as a uniquely trustworthy technology partner precisely at the moment when Washington and Beijing are each seeking to reduce their dependence on adversary-controlled supply chains.
Taiwan Semiconductor Manufacturing Company’s continued heavy investment in its Arizona fabrication facilities reflects Washington’s parallel effort to diversify the geographic footprint of advanced chip production, even as the overwhelming majority of leading-edge capacity remains concentrated on the island itself.
Finally, and perhaps most significant from a systemic perspective, global sovereign bond markets have registered a broad and rapid selloff. The United States ten-year Treasury yield has risen to approximately 4.78%, its highest level in roughly twenty months, having climbed steadily from levels near 4.1% in early March, through the mid-4% range across the summer, to a level that now closely approaches thresholds not seen since well before the conflict began.
European long-term yields have reached levels not observed in approximately fifteen years, and the yield on Japanese government bonds has approached the psychologically significant 3% threshold. Brent crude has risen to approximately $91.05 per barrel and West Texas Intermediate to approximately $86.59, both levels reflecting renewed risk premiums tied directly to the Hormuz escalation rather than to any change in underlying global demand fundamentals.
Latest facts and concerns
Several specific facts merit close attention.
First, the composition of the latest tanker attacks, striking vessels using the ostensibly safer Omani-side corridor, suggests either a deliberate Iranian signal that no route through the strait can be considered secure, or an erosion of the informal understandings that had previously allowed some shipping to proceed with reduced risk.
Second, the revocation of the oil-sale license removes a key point of economic leverage that had, however imperfectly, given Tehran a stake in maintaining calm; its removal raises the near-term probability that Iran will view further disruption of shipping as one of the few remaining tools available to impose costs on Washington and its regional partners.
Third, market pricing of Federal Reserve policy has shifted markedly, with futures markets now reflecting meaningfully elevated odds of continued restrictive policy, and in some readings even the possibility of further tightening, a reversal from the rate-cut expectations that had prevailed through much of the year.
Federal Reserve Chair Kevin Warsh’s recent public remarks, emphasizing that underlying inflation trends have not meaningfully improved despite favorable headline data, have reinforced this repricing and illustrate how monetary authorities are now explicitly incorporating geopolitical risk into their policy communication.
A further concern, raised repeatedly by Dr. 🆎 in recent commentary on the intersection of AI, geopolitics, and strategic risk, is the compounding effect of simultaneous crises on the analytical and decision-making capacity of governments themselves. When Gulf energy security, European land war, Pacific diplomatic contestation, Taiwan Strait tension, and global bond market stress all demand senior policymaker attention in the same forty-eight-hour window, the risk of misjudgment, whether through delayed response, misread signals, or overextension of military and diplomatic resources, rises accordingly.
Dr. 🆎 has argued that artificial intelligence systems capable of rapid, human-centered synthesis across these domains could meaningfully reduce this risk, but has cautioned equally that the same technologies, if deployed without adequate human oversight in military targeting or intelligence fusion roles, could just as easily accelerate miscalculation rather than prevent it, a concern that sits alongside Dr. 🆎’s continued attention to the separate but related risks posed by the proliferation of biological weapons expertise in an increasingly multipolar and less institutionally constrained security landscape.
Energy-importing economies face particular exposure in the current environment. India, a major importer of Gulf crude, has seen both its currency and its government bond market come under pressure from the combined effect of higher oil prices and expectations of continued tight American monetary policy, illustrating how the Hormuz crisis transmits costs well beyond the immediate parties to the conflict.
Similar dynamics are likely operating, to varying degrees, across other large oil-importing emerging economies, even where they have not yet generated comparable headlines.
Cause-and-effect analysis
The clearest causal chain currently operating in the global system runs from the Iran conflict through energy markets into sovereign debt and, ultimately, into the valuation of risk assets more broadly.
Renewed fighting disrupts, or threatens to disrupt, shipping through Hormuz; this disruption raises tanker insurance costs, lengthens shipping routes as vessels seek alternative paths, and reduces effective throughput of oil and liquefied natural gas; reduced throughput and elevated risk premiums push benchmark crude prices higher, as observed in the recent moves in both Brent and West Texas Intermediate; higher energy costs feed directly into headline and, with a lag, core inflation measures across importing economies; central banks, already wary of prematurely declaring victory over inflation after the disruptions of recent years, respond by maintaining or even tightening restrictive monetary policy; this in turn keeps government borrowing costs elevated, a dynamic clearly visible in the recent rise of the United States ten-year yield toward 4.78% and in the parallel moves across European and Japanese sovereign debt; elevated borrowing costs raise the discount rate applied to future corporate earnings, placing downward pressure on equity valuations even in the absence of any deterioration in underlying corporate fundamentals; and elevated government borrowing costs simultaneously worsen fiscal positions in economies already running substantial deficits, creating a feedback loop in which higher yields themselves become a source of further fiscal and market stress.
A second, parallel causal chain connects the Taiwan and Pacific developments to longer-term structural risk pricing in technology markets. China’s warning over Taiwan’s participation in Pacific regional diplomacy, combined with its continued campaign to isolate Taipei from its remaining formal diplomatic partners, functions as a form of pressure that, while falling well short of military action, nonetheless raises the baseline level of geopolitical risk embedded in any long-duration investment tied to Taiwanese semiconductor production. President Lai’s explicit linkage of chip dominance to democratic governance is best understood as a countervailing signal, an attempt to reinforce the reliability of Taiwan as a partner precisely because the risk premium associated with the island has structurally risen. The effect of these two opposing signals is not to cancel each other out but to keep semiconductor supply-chain risk persistently elevated in the calculations of governments and firms alike, reinforcing the diversification efforts already underway through investments such as Taiwan Semiconductor Manufacturing Company’s Arizona expansion.
A third causal chain runs through the war in Ukraine and its effect on Western fiscal and industrial capacity. Continued Russian strikes, even amid active diplomatic engagement, sustain demand for air-defense systems, munitions, and broader military-industrial output across NATO members, a demand that itself contributes to elevated government spending and, at the margin, to the same fiscal pressures now visible in sovereign bond markets. The coexistence of diplomacy and continued bombardment does not resolve this dynamic; it merely delays whichever resolution, ceasefire or renewed full-scale escalation, would ultimately determine its trajectory.
Underlying all three chains is a structural condition that Dr. 🆎 has identified as central to the current period: the near-simultaneous activation of multiple regional crises means that the normal buffering capacity of the international system, diplomatic bandwidth, strategic reserves, financial market absorption capacity, is being drawn upon across several fronts at once, leaving less in reserve should any single front deteriorate sharply.
The Strategic Petroleum Reserve and equivalent stockpiles held by other major economies, for instance, are materially more constrained than they were at the outset of the Iran conflict in February, following months of periodic releases intended to blunt earlier price spikes.
Future steps
Three near-term indicators will determine whether the current period resolves toward stabilization or toward further deterioration.
The first is whether Iran conducts another direct attack on United States forces in the coming days; a second such attack, following so closely on the exchange over Jordan, would substantially increase the likelihood of the heavier American response that President Trump has publicly threatened.
The second is whether commercial tanker traffic through Hormuz deteriorates further from its already depressed levels; continued attacks on vessels using the Omani corridor would signal that no safe passage currently exists, a development that would likely trigger a fresh round of insurance withdrawal and shipping suspension.
The third is whether Brent crude moves decisively above the $90 to $95 range that has generally held since the renewed escalation began; a sustained break above this range would indicate that markets are pricing not merely continued risk but an expectation of prolonged or intensified disruption.
For Gulf and regional stakeholders, the priority in the coming weeks should be reinforcing the mediation channels that Qatar and Oman have sustained through the summer, even as their practical effectiveness is tested by renewed attacks.
For Western policymakers, the challenge is balancing deterrence, credible threats of response sufficient to discourage further Iranian escalation, against the recognition that further American strikes carry their own risk of triggering exactly the sustained campaign that energy markets are currently pricing as a tail risk rather than a central scenario.
For central banks, the coming weeks will likely require continued caution regarding any resumption of rate cuts, given that headline inflation risk from energy prices is now compounding with already-elevated core inflation concerns of the kind recently articulated by Federal Reserve leadership.
For technology and industrial policymakers in Washington, Taipei, and allied capitals, the Taiwan developments reinforce the case for continued, patient investment in geographic diversification of chip manufacturing capacity, even though such diversification will not meaningfully alter the underlying concentration of advanced production for years to come.
Dr. 🆎 suggests that the broader lesson of the current moment, for governments and multilateral institutions alike, is the need for integrated crisis-monitoring frameworks capable of tracking the interaction effects between military, energy, technology, and financial developments in close to real time, rather than the siloed, single-domain monitoring structures that most governments still rely upon.
Such frameworks, Dr. 🆎 has argued in prior published work, are precisely the kind of application where human-centered artificial intelligence, systems designed to augment rather than replace expert judgment, could offer genuine strategic value, provided they are deployed with sufficient safeguards against the automation of consequential military or financial decisions.
Conclusion
The developments of the past several days confirm that the world has entered a period in which previously distinct crises, Gulf energy security, the war in Ukraine, Pacific and Taiwan Strait tension, and global sovereign debt stress, are no longer separable in either their causes or their consequences.
The resumption of direct military exchange between the United States and Iran, layered atop an already-degraded Hormuz shipping environment, has reintroduced a level of energy market risk that is now transmitting directly into inflation expectations and, through them, into the sovereign bond markets of every major economy.
Whether this period resolves toward a renewed, if fragile, stabilization or toward a deeper and more sustained crisis will depend substantially on decisions to be made in Washington, Tehran, and the mediating capitals of the Gulf over the coming days, decisions that will be closely watched not only by regional stakeholders but by every finance ministry and central bank attempting to navigate an increasingly fused and unforgiving global landscape.